MORTGAGE BROKER - FIRST HOME BUYERS

Buy your first home with a clear plan.

Know what you can borrow, what you'll need upfront and which loan options suit you, so you can make an offer knowing where you stand.

Book a Discovery Call →

★ 5.0 rating

70 Google reviews

13+ years

Broking experience

50+

Lenders compared

Australia-wide

Online appointments
WHAT TO UNDERSTAND BEFORE YOU BUY

Buying your first home shouldn’t feel like guesswork

Before making offers, understand what you can comfortably afford, the funds required and when to prepare.

How much can I comfortably afford?

A lender’s maximum assessment may not suit your repayments, expenses and lifestyle.

Do I have enough funds to buy?

Consider your deposit, purchase costs, lender requirements, available support and cash buffer together.

When should I prepare my finances?

The right time to explore pre-approval depends on your readiness and buying timeframe.

How do I choose a suitable loan?

Compare the rate with fees, repayments, structure, flexibility and future plans.


You don’t need every answer - just a clear way to work through the right questions.

WHY THE FINANCE ARCHITECT

More than help getting your first home loan.

Most first-home buyers need more than a lender comparison. We give you a clear process, straightforward explanations and support that continues beyond settlement.

Clear guidance without the jargon: Understand your options, trade-offs and next steps without feeling overwhelmed.

Support from first conversation to settlement: We manage the process and keep you informed along the way.

A plan beyond the purchase: For those wanting more direction, our Debt-Free Home Strategy adds a personalised roadmap, milestones and ongoing accountability.
OUR PROCESS

From discovery call to ongoing review

01

Discovery Call

Discuss your position, goals, timing and questions.

02

Assess

Review your finances, commitments, deposit and future plans.

03

Recommend

Explain the options and trade-offs, recommend a strategy and prepare for pre-approval.

04

Apply & settle

Coordinate the application, lender requirements and settlement.

05

Review

Review the loan as your circumstances, goals and lending conditions change.

CLIENT EXPERIENCES

What our first home buyer clients say

★★★★★

5.0 · Based on 70 Google reviews
Kimberly
★★★★★
Dale is friendly, professional and makes a daunting experience for first home buyers like myself and my partner super easy to understand.
Declan
★★★★★
From start to finish, Dale and his team made financing feel friendly, simple and understandable. Dale consistently put himself in our shoes, and offered guidance and support every step of the way.
Liz
★★★★★
I was going in dreading the process and worried it would be complicated and overwhelming but Dale made everything really easy to understand and turned everything around so quickly.
Luna
★★★★★
From day one, they were incredibly helpful, supportive, and patient, answering all my questions along the way.
Sean
★★★★★
It was invaluable getting Dale's advice two years ago in budgeting and setting up my finances correctly to ensure that I would be ready to purchase a property.
Melanie
★★★★★
They have always been there to answer our questions and guide us through the process.
Caitlan
★★★★★
Dale and the team were great to work with during the purchase of my first home. I really appreciated all their help and support throughout the process. Thank you!
Amy
★★★★★
They went out of their way to make me feel very comfortable and confident with the process.
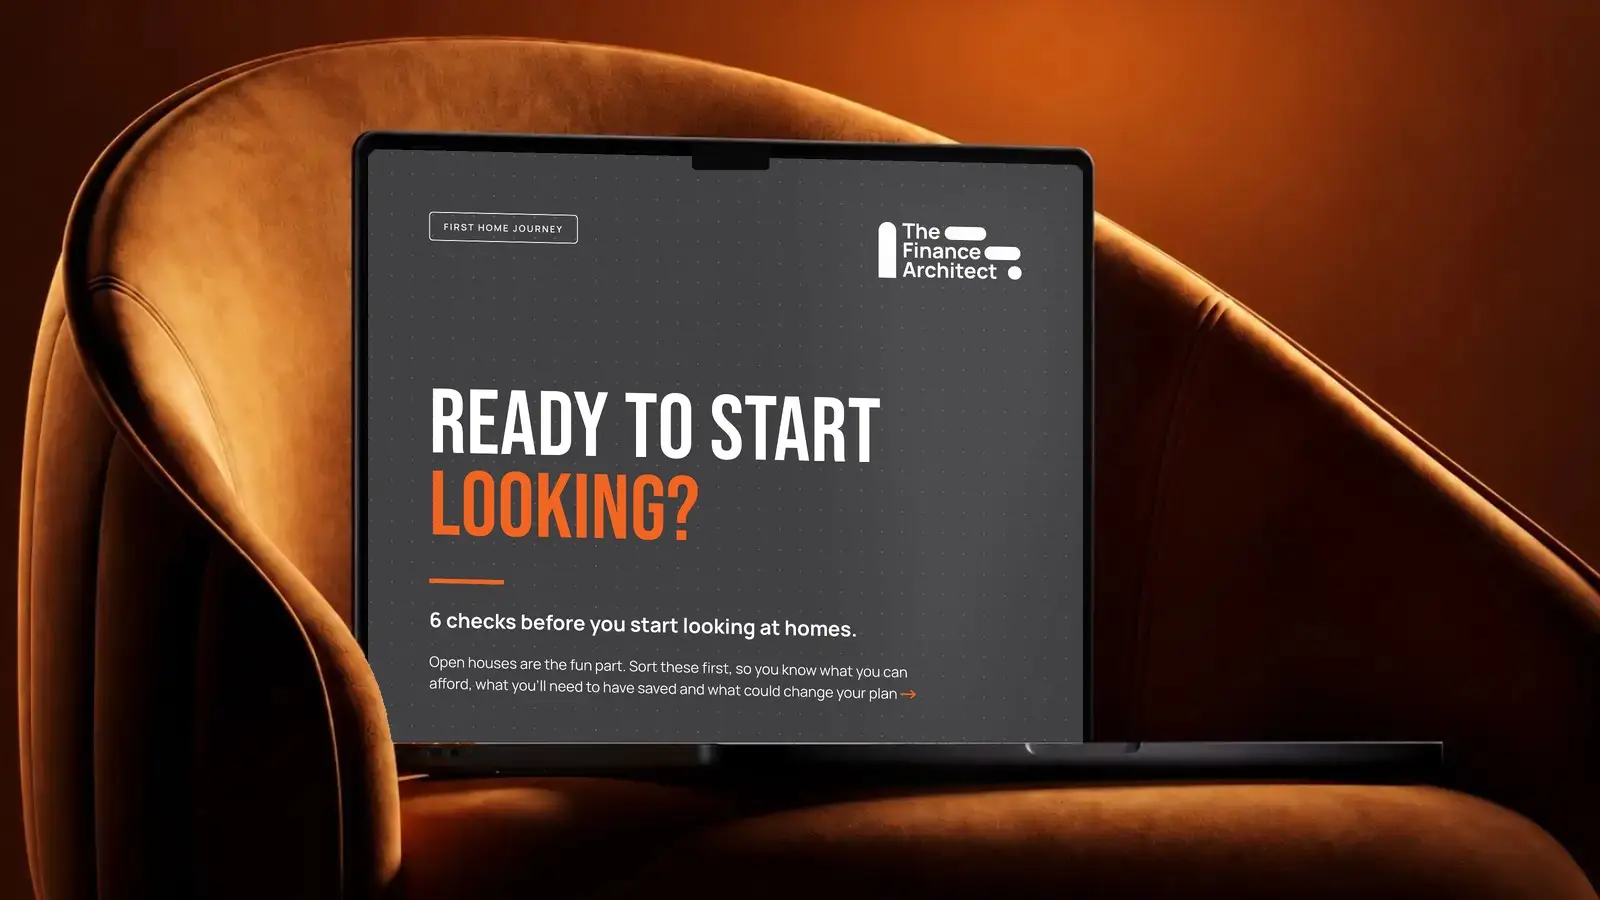
Laptop on an orange armchair showing the cover of The Finance Architect’s first home buyer checklist, “Ready to start looking? 6 checks before you start looking at homes.

FREE FIRST HOME BUYER CHECKLIST

Ready to start looking?

Six checks to work through before you start looking at homes, from a budget you’re comfortable with to the costs on top of your deposit.

We'll also email you a copy and occasional insights. Unsubscribe anytime.

FIRST-HOME BUYER FAQs

Your first-home questions, answered

How much you can borrow depends on your income, living expenses, existing debts, financial commitments and the lender’s assessment criteria. Lenders also test whether you could continue to afford the loan if interest rates were higher, so borrowing capacity can vary between lenders even when your circumstances stay the same.

Your maximum borrowing amount is also different from what you may be comfortable spending each month. At The Finance Architect, we look at both your borrowing capacity and a realistic purchase budget so you can understand what you may be able to borrow without losing sight of what comfortably fits your finances.

The deposit you need depends on the property price, the lender and whether you qualify for a low-deposit or government-supported option. A 20% deposit can help you avoid lenders mortgage insurance, but some lenders may accept a much smaller deposit, and eligible first-home buyers may be able to use government support to buy with less.

You’ll also need to allow for buying costs such as conveyancing, inspections and any applicable duties, rather than putting every dollar into the deposit.

We help you work out the deposit you may need and what should remain available for the rest of the purchase.

Read our full guide: how much deposit do you need to buy your first home?

Home loan pre-approval is an indication from a lender that, based on the information you’ve provided, you may be eligible to borrow up to a certain amount. The lender will usually assess your income, expenses, debts, savings and credit history, and may ask for supporting documents.

Pre-approval can help you set a realistic price range, but it is not the same as final loan approval and will usually only remain valid for a limited period.

We help you understand what your pre-approval means, what conditions may still apply and how it fits with a purchase budget you’re comfortable with.

The grants and schemes available to you depend on where you’re buying, the property type and value, and your personal eligibility.

Support can include state-based First Home Owner Grants, stamp duty concessions or exemptions, and federal low-deposit home buyer programs; the rules and thresholds vary and can change over time.

In Victoria, for example, eligible first-home buyers may qualify for a $10,000 First Home Owner Grant on certain new homes up to $750,000, as well as duty savings on eligible purchases. (Last reviewed: October 2026)

We help you identify which options may be relevant to your purchase and factor them into your deposit, borrowing and overall buying plan.

A guarantor home loan allows someone, usually a close family member, to use part of their own property as additional security for your loan. This can help some first-home buyers purchase sooner with a smaller deposit and may reduce or avoid lenders mortgage insurance, depending on the lender and structure.

The guarantor takes on real financial risk because they may be required to repay the guaranteed amount if you cannot meet the loan obligations, so independent legal advice is important before proceeding.

We can help assess whether a guarantor structure is appropriate and explain how it may fit within your broader home-buying plan.

GET STARTED

Know what your next step looks like

Whether you're still saving or ready to make an offer, a Discovery Call can clarify what to address now and what comes next.

Book a Discovery Call →