An investment property loan funds a property you plan to hold as an investment rather than live in. It works much like a home loan, but lenders assess it differently.
How you structure it also matters beyond this one purchase. It shapes your cash flow, your flexibility and your ability to borrow again. Here’s how it works, what lenders look at and what to consider before you apply.
Key points
- Lenders assess your whole financial position, and most count only part of the expected rent.
- A 20% deposit is a common benchmark, not a rule. Equity in a property you already own may help fund the purchase.
- Interest-only lowers repayments for a set period, but usually costs more interest overall. In our example, about $37,600 more over 30 years.
What is an investment property loan?
An investment property loan is finance to buy a property you’ll rent out or hold as an investment. The property you buy is usually the security for the loan.
It may have a fixed or variable rate, with principal-and-interest or interest-only repayments. Because it’s for investment, not a home you live in, lenders may assess and price it differently.
You’re responsible for the repayments however much rent the property earns, even if it’s empty for a time or its value falls.
How do lenders assess an investment property loan?
Lenders start with the same basics as a home loan. They then add the income, costs and risks of holding a rental property. The question is whether you can afford the new loan alongside everything else you owe.
- Your income: salary and other income the lender accepts.
- Expenses and debts: living costs, existing home and investment loans, credit cards and other commitments.
- The property: the lender may value it to work out the loan-to-value ratio (LVR). LVR can affect which products you can get, the rate, and whether lenders mortgage insurance (LMI) applies.
- Repayment type: principal-and-interest or interest-only can change the assessment.
- Rental income: covered below.
Each lender applies its own rules. The same income, rent, debts and property value can lead to different outcomes with different lenders. Your application is judged on your whole position, not just on whether the rent covers the mortgage.
How does rental income affect borrowing capacity?
Rent can add to your borrowing capacity, but lenders don’t usually count all of it. They often reduce it to allow for vacancies, management costs and changes in rent. How much they reduce it varies between lenders and properties.
For illustration: a property renting for $500 a week earns $26,000 a year. If a lender counts 80% of that, it uses $20,800 in its assessment. Lenders set their own percentages.
If you already own investment property, the lender will look at that rent and that debt too. Rent is only one part of the picture. Your application still has to meet the lender’s credit and affordability rules.
How much deposit do you need for an investment property?
There’s no single amount. It depends on the lender, the property, your finances and the LVR the lender will accept.
A 20% deposit is a common benchmark because it can reduce or avoid LMI. It isn’t a fixed rule. Some lenders accept less, and some ask for more depending on the property or application.
Your deposit is separate from buying costs like transfer duty, conveyancing and inspections. And having the deposit isn’t enough on its own. Your borrowing capacity and the lender’s criteria still need to support the whole loan.
Can you use equity to buy an investment property?
Often, yes. If you already own a property, some of its equity may help fund the deposit and buying costs.
Equity is the difference between a property’s value and what you owe on it, but you can’t borrow all of it. How much you can use depends on the lender’s valuation, its maximum LVR, your current loan, your borrowing capacity and its credit policy.
How you access the equity matters too. You might increase your current loan, set up a separate loan split or use another security structure. Each works differently. Using your home as extra security, for example, can tie the two properties together, so understand the setup and the risks first.
Keeping your current home as an investment and buying your next one? See buying your next home before selling.
Which repayment type suits an investment loan?
Depending on the lender and product, you may be able to choose principal-and-interest or interest-only repayments.
| Principal and interest | Interest-only | |
|---|---|---|
| Each repayment | Covers the interest and part of the loan balance. | Usually covers only the interest, for an agreed period. |
| Loan balance | Reduces from the first repayment. | Usually stays the same during the interest-only period, unless you pay extra. |
| Cash flow | Higher required repayments initially. | Lower repayments during the interest-only period. |
| Total interest | Lower over the life of the loan, all else being equal. | Can be higher, because the balance isn’t falling. |
| When the period ends | No change. | Usually switches to principal and interest over the remaining term, so repayments rise. |
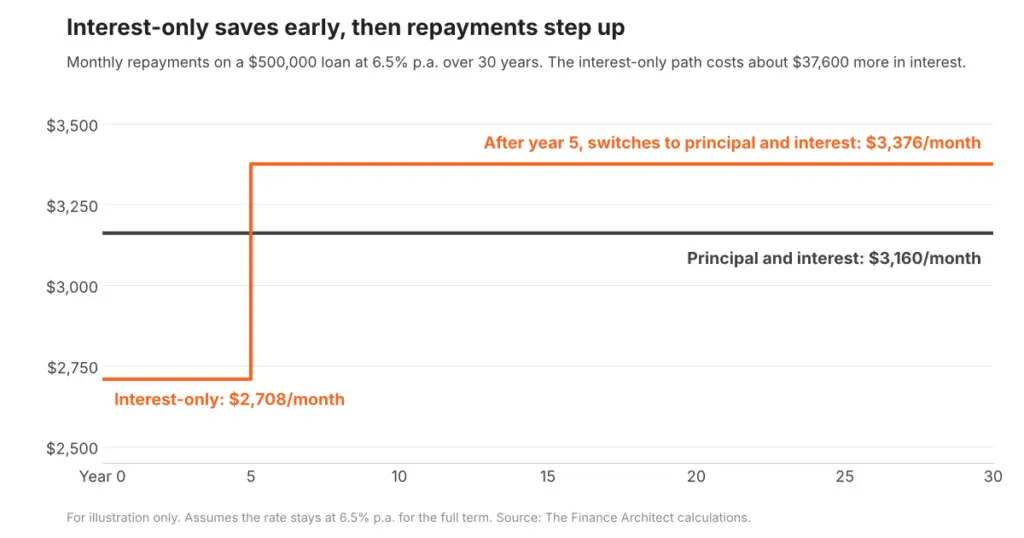
For illustration, take a $500,000 loan at 6.5% p.a. over 30 years:
- Principal and interest: about $3,160 a month for the full term.
- Interest-only for five years: about $2,708 a month. The loan then switches to principal and interest over the remaining 25 years, and repayments rise to about $3,376 a month.
- Over the full 30 years: the interest-only path costs about $37,600 more in interest.
Interest-only can ease cash flow in the short term, but that doesn’t make it the better structure. It isn’t a default for investors, and it isn’t a tax strategy. The right choice depends on your cash flow, goals, lender policy and wider borrowing position. Check any tax implications with a registered tax adviser.
Moneysmart’s interest-only home loans guide and interest-only calculator show how repayments change when an interest-only period ends.
What costs should you allow for when buying an investment property?
An investment property costs more than the deposit and repayments. Allow for the upfront costs of buying and the ongoing costs of owning it.
- Upfront: transfer duty, conveyancing or legal fees, building and pest inspections, loan or valuation fees, and LMI if it applies.
- Ongoing: council and water rates, insurance, strata or body corporate fees, property management, maintenance and repairs.
- Vacancy: times when the property is empty and earns no rent.
These costs affect the cash you need to buy and the property’s cash flow afterwards. Some may also form part of the lender’s assessment.
Tax treatment depends on the expense and your situation. Confirm deductions, depreciation and other tax outcomes with your accountant or a registered tax adviser. Moneysmart’s guide to buying an investment property covers the ongoing costs to budget for.
Why does loan structure matter, and how does it affect your next property?
When you apply for your next property, your first investment loan becomes part of what the lender assesses. So how you set it up affects more than this purchase. Structure includes:
- Principal and interest or interest-only
- Whether you use separate loan splits
- How any equity release is set up
- Whether personal and investment borrowing are kept apart
Mixing personal and investment debt in the same loan or redraw can complicate your records, including for tax. Check the consequences with your accountant.
For your next application, a lender will look at your current loan balance, repayments and other debts. It may count some of the rent from your first property. Repayment type matters too: principal and interest reduces the balance over time, while interest-only may leave it unchanged. Equity may help later, but don’t assume the property will rise in value or that you can use all of the equity.
That’s why the lowest rate isn’t the only thing to compare. A loan that suits this purchase can make the next one harder if it reduces your flexibility.
The ATO explains which interest expenses on a rental property can be claimed. Ask your accountant how this applies to you.
Investment property loan FAQs
How much can I borrow for an investment property?
There’s no single amount. A lender looks at your income, the rent it accepts, your living costs, existing debts, the new loan, the property value and its own serviceability rules. Your borrowing capacity can differ from one lender to the next.
Are investment property loan rates higher?
They can be, but not always. Lenders may price investment loans differently, and rates also vary with LVR, repayment type, product and borrower. Compare the whole loan, not just the headline rate.
Is it harder to get an investment loan than an owner-occupier loan?
Not necessarily harder, but assessed differently. Lenders weigh rental income, existing investment debts and property costs alongside your income and expenses, and their policies vary. A broker can compare how different lenders would treat your situation.
Can an investment property loan be interest-only?
Yes, with some lenders, subject to their criteria. The balance usually doesn’t fall during the interest-only period, and repayments may rise when it switches to principal and interest.
Can I refinance an investment property loan?
Yes, if the lender approves. Refinancing may let you change the rate, features, repayment type or lender, but switching costs and the remaining term matter. The test is whether you’re better off after costs. See when refinancing makes sense.
Can I use my home as security for an investment property?
Some lenders allow it, but it isn’t the only option. Using more than one property as security is often called cross-collateralisation. It ties the properties together, so understand the setup, the equity involved and the risks first.
Do lenders count all of the rent from an investment property?
Usually not. Lenders often allow for vacancies and changes in rent, and may factor in property costs. The amount they accept varies.
Do I need a 20% deposit for an investment property?
Not necessarily. A 20% deposit is a common benchmark, but requirements vary. Some lenders accept less, and some ask for more.
Can I have more than one investment property loan?
Yes. There’s no simple limit, but each new property and loan becomes part of your next assessment, along with your borrowing capacity, rental income, repayments, equity and lender policy.
Your investment plan
Treat an investment loan as part of your wider borrowing position, not just a way to fund one purchase. The best structure isn’t always the one with the lowest rate or the smallest first repayment.
At The Finance Architect, we work with property investors to structure lending around the property you’re buying now and what you may want to do next.
Thinking about an investment property? Book a Discovery Call with Dale to work through your borrowing position and loan options.